UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 8-K
CURRENT REPORT
Pursuant to Section 13 or 15(d) of
the Securities Exchange Act of 1934
Date of Report (date of earliest event reported): November 4, 2026
(Exact name of registrant as specified in its charter)
| (State or other jurisdiction of incorporation) | (Commission File Number) | (I.R.S. Employer Identification No.) | ||||||||||||
| | ||||||||||||||
| (Address of principal executive offices) | (Zip Code) | |||||||||||||
Registrant's telephone number, including area code: (713 ) 960-9111
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions:
| Written communications pursuant to Rule 425 under the Securities Act (17 CFR 230.425) | |||||
| Soliciting material pursuant to Rule 14a-12 under the Exchange Act (17 CFR 240.14a-12) | |||||
| Pre-commencement communications pursuant to Rule 14d-2(b) under the Exchange Act (17 CFR 240.14d-2(b)) | |||||
| Pre-commencement communications pursuant to Rule 13e-4(c) under the Exchange Act (17 CFR 240.13e-4(c)) | |||||
Securities registered pursuant to Section 12(b) of the Act:
| Title of each class | Trading Symbol(s) | Name of each exchange on which registered | ||||||
NYSE Texas | ||||||||
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (§230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§240.12b-2 of this chapter).
Emerging growth company ☐
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ◻
Item 2.02. Results of Operations and Financial Condition.
On November 4, 2026 , Westlake Corporation (the "Company"), issued a press release announcing its 2026 third quarter results. A copy of the press release is furnished with this Current Report as Exhibit 99.1.
The information furnished pursuant to this Current Report, including Exhibit 99.1, shall not be deemed to be "filed" for the purposes of Section 18 of the Securities Exchange Act of 1934, as amended, and will not be incorporated by reference into any registration statement filed by Westlake Corporation under the Securities Act of 1933, as amended, unless specifically identified as being incorporated therein.
Item 7.01. Regulation FD Disclosure.
The Company is holding a conference call on November 4, 2026 to discuss its 2026 third quarter results. Information about the call can be found in the press release furnished with this Current Report as Exhibit 99.1. In addition, the Company made available an investor presentation regarding its 2026 third quarter results, which is furnished with this Current Report as Exhibit 99.2.
Item 9.01. Financial Statements and Exhibits.
(d) Exhibits
The following exhibits are furnished herewith:
104 The cover page from this Current Report on Form 8-K, formatted in Inline XBRL.
SIGNATURE
Pursuant to the requirements of the Securities Exchange Act of 1934, the Registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized.
WESTLAKE CORPORATION | ||||||||||||||
| Date: | By: | /S/ JEAN-MARC GILSON | ||||||||||||
| Jean-Marc Gilson | ||||||||||||||
President, Chief Executive Officer and Director (Principal Executive Officer) | ||||||||||||||
EXHIBIT 99.1
WESTLAKE CORPORATION
Contact—(713) 960-9111
Investors—Jeff Holy
Media—L. Benjamin Ederington
Westlake Corporation Reports Third Quarter 2026 Results
HOUSTON, Nov. 04, 2026 (GLOBE NEWSWIRE) --Westlake Corporation (NYSE: WLK) (the "Company" or "Westlake") today announced third quarter 2026 results.
SUMMARY FINANCIAL HIGHLIGHTS (in millions of dollars, except per share data and percentages)
| Three Months Ended September 30, 2026 | Three Months Ended June 30, 2026 | Three Months Ended September 30, 2025 | ||||||||||||||||||
| Westlake Corporation | ||||||||||||||||||||
| Net sales | $ | 2,981 | $ | 3,271 | $ | 2,838 | ||||||||||||||
| Income (loss) from operations | $ | 43 | $ | 364 | $ | (766) | ||||||||||||||
| Net income (loss) attributable to Westlake Corporation | $ | 6 | $ | 260 | $ | (782) | ||||||||||||||
| Diluted earnings (loss) per common share | $ | 0.05 | $ | 2.01 | $ | (6.06) | ||||||||||||||
Identified Items (1) | $ | 58 | $ | — | $ | 744 | ||||||||||||||
| Net income (loss) attributable to Westlake Corporation excl. Identified Items | $ | 58 | $ | 260 | $ | (38) | ||||||||||||||
| Diluted earnings (loss) per common share excl. Identified Items | $ | 0.45 | $ | 2.01 | $ | (0.29) | ||||||||||||||
| EBITDA | $ | 350 | $ | 679 | $ | (431) | ||||||||||||||
| EBITDA excl. Identified Items | $ | 408 | $ | 679 | $ | 313 | ||||||||||||||
| EBITDA margin excl. Identified Items | 14% | 21% | 11% | |||||||||||||||||
| Housing and Infrastructure Products ("HIP") Segment | ||||||||||||||||||||
| Net sales | $ | 1,087 | $ | 1,252 | $ | 1,091 | ||||||||||||||
| Income from operations | $ | 128 | $ | 212 | $ | 151 | ||||||||||||||
| EBITDA | $ | 195 | $ | 276 | $ | 215 | ||||||||||||||
| EBITDA excl. Identified Items | $ | 195 | $ | 276 | $ | 215 | ||||||||||||||
| EBITDA margin excl. Identified Items | 18% | 22% | 20% | |||||||||||||||||
| Performance and Essential Materials ("PEM") Segment | ||||||||||||||||||||
| Net sales | $ | 1,894 | $ | 2,019 | $ | 1,747 | ||||||||||||||
| Income (loss) from operations | $ | (64) | $ | 185 | $ | (902) | ||||||||||||||
| EBITDA | $ | 159 | $ | 416 | $ | (654) | ||||||||||||||
Identified Items (1) | $ | 56 | $ | — | $ | 744 | ||||||||||||||
| EBITDA excl. Identified Items | $ | 215 | $ | 416 | $ | 90 | ||||||||||||||
| EBITDA margin excl. Identified Items | 11% | 21% | 5% | |||||||||||||||||
(1)For the three months ended September 30, 2026, Identified Items include $56 million of charges related to previously announced facility shutdowns in PEM and $2 million of other restructuring costs. For the three months ended September 30, 2025, Identified Items represent a non-cash impairment charge of $727 million representing all of the goodwill associated with the North American Chlorovinyls reporting unit and $17 million of charges related to previously announced facility shutdowns.
i
BUSINESS HIGHLIGHTS
Westlake reported third quarter of 2026 net sales of $3.0 billion, net income of $6 million, or $0.05 per share, and EBITDA (earnings before interest expense, income taxes, depreciation and amortization) of $350 million. Excluding Identified Items, net income in the third quarter of 2026 was $58 million, or $0.45 per share, and EBITDA was $408 million.
Compared to the third quarter of 2025, the Company's average sales price increased 6% while comparable sales volume was unchanged (excluding the effects of acquisitions and plant closures). Reported HIP sales were relatively unchanged as a 6% decline in comparable sales volume was offset by a 1% increase in average sales price and 5% contribution from the ACI acquisition. Reported PEM sales increased 8% over the same period of time due to a 9% increase in average sales price and a 4% increase in comparable sales volume that were partially offset by a 5% net reduction to sales from plant closures partially offset by the Wilhelmshaven acquisition. EBITDA margin excluding Identified Items increased from 11% to 14%, primarily due to the increase in PEM's average sales price and benefits from our three-pillar profitability improvement plan that more than offset higher costs.
Compared to the second quarter of 2026, the Company's average sales price declined 4% while comparable sales volume declined 7% (excluding the effect of the Wilhelmshaven acquisition). The Company's sales and earnings were impacted by an 8% sequential decline in PEM's average sales price in the third quarter of 2026 as second quarter price increases at the onset of the Middle East conflict moderated, but were still above levels from the third quarter of 2025 and have recently inflected higher off the lows of the quarter. HIP's 17% sequential sales volume decline reflected volume shifts between quarters and the industry-wide trend of slowing residential construction activity while margins were impacted by higher distribution costs.
Financial conditions for the European chemical industry meaningfully deteriorated during the third quarter of 2026 due to significantly higher energy costs, weak demand, and increasing imports. Taking into consideration the structural challenges in Europe, the Company is taking action to optimize its European chlorovinyls footprint by integrating its globally-advantaged North American chlorovinyls assets with the recently-acquired vinyls facility in Wilhelmshaven, Germany, and removing higher-cost capacity from its system with the announced closure of its PVC plant in Cologne, Germany.
EXECUTIVE COMMENTARY
"Our third quarter of 2026 financial results reflected lower levels of North American residential construction activity and customer inventory destocking in our HIP segment combined with lower selling prices and margins in our PEM segment as initial price increases realized in the second quarter of 2026 following the onset of the Middle East conflict moderated. Earnings in PEM's European businesses were significantly impacted by higher energy costs, weak demand, and increased import pressure from Asia. In response to these structural challenges in Europe, we took action to optimize our footprint in the third quarter by announcing the closure of a PVC plant in Cologne, Germany. HIP's third quarter margins were also impacted by higher diesel and freight costs. Despite these headwinds, Westlake generated $220 million of free cash flow during the quarter, in part due to the benefits from our three-pillar profitability improvement plan, which remains on track to deliver $600 million of EBITDA uplift in 2026," said Jean‑Marc Gilson, President and Chief Executive Officer.
"Higher borrowing costs have increased potential homebuyers' affordability concerns, which we expect to weigh on HIP's near-term sales volumes. Nevertheless, we remain positive on the medium- to long-term outlook for HIP sales and earnings growth supported by our investments in growth segments of the market and infrastructure spending. While PEM selling prices have stabilized with upward momentum entering the fourth quarter of 2026, we recognize that an environment of heightened price volatility persists, which requires us to stay vigilant in identifying and executing cost reduction and footprint optimization actions," Mr. Gilson concluded.
"Our investment-grade rated balance sheet, with $2.0 billion of cash and investments at the end of the third quarter continues to be a differentiated source of strength for Westlake that supports our ability to continue to invest in attractive markets, such as our recent roofing acquisition and the acquisitions of both ACI and Wilhelmshaven earlier in 2026, while continuing to return cash to shareholders through a solid dividend that has grown for 22 consecutive years since our IPO in 2004," added Jon Baksht, Senior Vice President and Chief Financial Officer.
RESULTS
Consolidated Results
(Unless otherwise noted the financial numbers below exclude the effects of the Identified Items)
ii
For the three months ended September 30, 2026, the Company reported quarterly net income of $58 million, or $0.45 per share, on net sales of $3.0 billion compared to the net loss of $38 million reported in the third quarter of 2025. Compared to the prior year period, earnings benefited from a higher average sales price and margin in PEM, our three-pillar profitability improvement plan, and the ACI acquisition, which were partially offset by higher distribution and ethane costs.
EBITDA of $408 million for the third quarter of 2026 increased by 30% from the third quarter of 2025 EBITDA of $313 million. Third quarter 2026 EBITDA decreased by $271 million compared to second quarter of 2026 EBITDA of $679 million.
Reconciliations of non-GAAP financial measures used in this press release (including EBITDA and measures that exclude the effects of the Identified Items) to the most directly comparable GAAP measure can be found in the financial schedules at the end of this press release.
Expenses Regarding Facility Closures and the Chlorovinyls Impairment ("Identified Items")
During the third quarter of 2026, the Company recorded $56 million of charges in PEM related to previously announced facility shutdowns, including the Cologne PVC facility, certain North American chlorovinyls facilities and a styrene facility in addition to $2 million of other restructuring costs. During the third quarter of 2025, the Company recorded a non-cash impairment charge of $727 million representing all of the goodwill associated with the North American Chlorovinyls reporting unit, and accrued $17 million of expenses related to previously announced asset shutdowns.
Cash, Investments and Debt
Net cash provided by operating activities was $408 million for the third quarter of 2026 and capital expenditures were $188 million. As of September 30, 2026, cash, cash equivalents and fixed-income investments were $2.0 billion and total debt was $5.1 billion.
Housing and Infrastructure Products Segment
(Unless otherwise noted the financial numbers below exclude the effects of the Identified Items)
For the third quarter of 2026, Housing and Infrastructure Products income from operations of $128 million decreased by $23 million as compared to the third quarter of 2025. The year-over-year decrease was the result of lower sales volume, particularly for pipe & fittings, and higher distribution costs. Housing Products net sales of $846 million in the third quarter of 2026 decreased by $82 million from the third quarter of 2025 primarily due to lower sales volume, particularly for roofing and siding & trim. Infrastructure Products net sales of $241 million increased by $78 million from the third quarter of 2025 primarily due to the January 2026 acquisition of ACI.
Sequentially, Housing and Infrastructure Products income from operations decreased by $84 million as compared to the second quarter of 2026. This decrease in income from operations versus the prior quarter was primarily due to lower sales volume, particularly for pipe & fittings with some demand shifting from the third quarter of 2026 into the second quarter of 2026 as customers sought to secure supply in the wake of the onset of the conflict in the Middle East.
Performance and Essential Materials Segment
(Unless otherwise noted the financial numbers below exclude the effects of the Identified Items)
For the third quarter of 2026, Performance and Essential Materials loss from operations was $8 million as compared to the third quarter of 2025's loss from operations of $158 million. The decrease in loss from operations was due to a 9% increase in average sales price and margin benefits from our three-pillar profitability improvement plan. Performance Materials net sales of $1.2 billion in the third quarter of 2026 increased by $166 million from the third quarter of 2025 primarily due to a higher average sales price for polyethylene and PVC resin. Essential Materials net sales of $718 million decreased by $19 million from the third quarter of 2025 primarily due to lower caustic soda sales volume partially due to plant shutdowns.
Sequentially, Performance and Essential Materials loss from operations of $8 million for the third quarter of 2026 was $193 million lower than the second quarter of 2026's income from operations of $185 million. This decrease in income from operations versus the prior quarter was primarily due to a lower average sales price, particularly for PVC resin and polyethylene, and higher European energy costs.
iii
Forward-Looking Statements
The statements in this release and the related teleconference relating to matters that are not historical facts, including statements regarding our outlook for the performance of our business segments and future earnings, global macroeconomic conditions and their effects on us and our customers, expectations regarding interest rates and building costs, trends in the global cost curve and any associated pricing and margin benefits, industrial and manufacturing activity in our target markets, including infrastructure spending and investment, expectations regarding cash flow improvements, our ability to pass higher costs to customers, future sales and earnings growth, our capital deployment strategy, growth in our customers' businesses and their dependence on our products, the effects of the conflict in the Middle East, our competitors and global supply chains, future global trading policy and relationships, housing demand and residential construction activity, raw material costs, fluctuations in energy and feedstock prices, our ability to execute against our profitability improvement plan and the effects of our optimization initiatives (including anticipated cost savings), our market position and the strength of our brands, the benefits of a diversified and integrated business model, our ability to maintain cost advantages and global demand for our products are forward-looking statements.
These forward-looking statements are subject to significant risks and uncertainties. Actual results could differ materially, based on factors including, but not limited to: general economic and business conditions; the cyclical nature of the chemical and building products industries; the availability, cost and volatility of raw materials and energy; uncertainties associated with the United States, European and worldwide economies, including those due to political tensions and conflict in the Middle East, Russia and Ukraine and elsewhere; uncertainties associated with pandemic infectious diseases; uncertainties associated with climate change; the potential impact on demand for ethylene, polyethylene and polyvinyl chloride due to initiatives such as recycling and customers seeking alternatives to polymers; current and potential governmental regulatory actions in the United States and other countries; industry production capacity and operating rates; the supply/demand balance for Westlake's products; competitive products and pricing pressures; instability in the credit and financial markets; access to capital markets; terrorist acts; operating interruptions; changes in laws and regulations, including trade policies and tariffs; the effects of government shutdowns; technological developments; information systems failures and cyberattacks; foreign currency exchange risks; our ability to implement our business strategies; creditworthiness of our customers; the effects and results of litigation and settlements of litigation; and other risk factors. For more detailed information about the factors that could cause actual results to differ materially, please refer to Westlake's Annual Report on Form 10-K for the year ended December 31, 2025, which was filed with the SEC in February 2026 and Westlake's Quarterly Report on Form 10-Q for the quarterly period ended June 30, 2026, which was filed with the SEC in August 2026.
Use of Non-GAAP Financial Measures
This release makes reference to certain "non-GAAP" financial measures, such as EBITDA, free cash flow and other measures that exclude the effects of the Identified Items, as defined in Regulation G of the U.S. Securities Exchange Act of 1934, as amended. For this purpose, a non-GAAP financial measure is generally defined by the Securities and Exchange Commission (SEC) as a numerical measure of a registrant's historical or future financial performance, financial position or cash flows that (1) excludes amounts, or is subject to adjustments that have the effect of excluding amounts, that are included in the most directly comparable measure calculated and presented in accordance with GAAP in the statement of operations, balance sheet or statement of cash flows (or equivalent statements) of the registrant; or (2) includes amounts, or is subject to adjustments that have the effect of including amounts, that are excluded from the most directly comparable measure so calculated and presented. We report our financial results in accordance with U.S. generally accepted accounting principles (U.S. GAAP), but believe that certain non-GAAP financial measures, such as EBITDA, free cash flow and measures that exclude the effects of the Identified Items, provide useful supplemental information to investors regarding the underlying business trends and performance of the Company's ongoing operations and are useful for period-over-period comparisons of such operations. These non-GAAP financial measures should be considered as a supplement to, and not as a substitute for or superior to, the financial measures prepared in accordance with U.S. GAAP. A reconciliation of (i) net income (loss), income (loss) from operations and net cash provided by operating activities to EBITDA, and (ii) net cash provided by operating activities to free cash flow and (iii) other measures reflecting adjustments for the effects of the Identified Items can be found in the financial schedules at the end of this press release.
iv
About Westlake
Celebrating 40 years of operations in 2026, Westlake is a global manufacturer and supplier of materials and innovative products that enhance life every day. Headquartered in Houston, with operations in Asia, Europe and North America, we provide the building blocks for vital solutions — from housing and construction, to packaging and healthcare, to automotive and consumer goods. For more information, visit the Company's web site at www.westlake.com.
Westlake Corporation Conference Call Information:
A conference call to discuss Westlake Corporation's third quarter 2026 results will be held Wednesday, November 4, 2026 at 11:00 AM Eastern Time (10:00 AM Central Time). To access the conference call, it is necessary to pre-register at https://register-conf.media-server.com/register/BIb43f6e616a634ff28258b88359118d2b. Once registered, you will receive a phone number and unique PIN number.
A replay of the conference call will be available beginning two hours after its conclusion. The conference call and replay will be available via webcast at https://edge.media-server.com/mmc/p/myjybcxp.
v
WESTLAKE CORPORATION
CONSOLIDATED STATEMENTS OF OPERATIONS
(Unaudited)
| Three Months Ended September 30, | Nine Months Ended September 30, | |||||||||||||||||||||||||
| 2026 | 2025 | 2026 | 2025 | |||||||||||||||||||||||
(in millions of dollars, except per share data and share amounts) | ||||||||||||||||||||||||||
| Net sales | $ | 2,981 | $ | 2,838 | $ | 8,904 | $ | 8,637 | ||||||||||||||||||
| Cost of sales | 2,599 | 2,602 | 7,758 | 7,911 | ||||||||||||||||||||||
| Gross profit | 382 | 236 | 1,146 | 726 | ||||||||||||||||||||||
| Selling, general and administrative expenses | 250 | 228 | 739 | 676 | ||||||||||||||||||||||
| Impairment of goodwill | — | 727 | — | 727 | ||||||||||||||||||||||
| Amortization of intangibles | 31 | 30 | 93 | 91 | ||||||||||||||||||||||
| Restructuring, transaction and integration-related costs | 58 | 17 | 79 | 139 | ||||||||||||||||||||||
| Income (loss) from operations | 43 | (766) | 235 | (907) | ||||||||||||||||||||||
| Interest expense | (52) | (41) | (163) | (120) | ||||||||||||||||||||||
| Other income, net | 17 | 32 | 84 | 93 | ||||||||||||||||||||||
| Income (loss) before income taxes | 8 | (775) | 156 | (934) | ||||||||||||||||||||||
| Provision for (benefit from) income taxes | (10) | (3) | 24 | 4 | ||||||||||||||||||||||
| Net income (loss) | 18 | (772) | 132 | (938) | ||||||||||||||||||||||
| Net income attributable to noncontrolling interests | 12 | 10 | 35 | 26 | ||||||||||||||||||||||
| Net income (loss) attributable to Westlake Corporation | $ | 6 | $ | (782) | $ | 97 | $ | (964) | ||||||||||||||||||
| Earnings (loss) per common share attributable to Westlake Corporation: | ||||||||||||||||||||||||||
| Basic | $ | 0.05 | $ | (6.06) | $ | 0.75 | $ | (7.48) | ||||||||||||||||||
| Diluted | $ | 0.05 | $ | (6.06) | $ | 0.75 | $ | (7.48) | ||||||||||||||||||
| Weighted average common shares outstanding: | ||||||||||||||||||||||||||
| Basic | 127,830,227 | 128,251,427 | 127,953,601 | 128,265,950 | ||||||||||||||||||||||
| Diluted | 127,962,530 | 128,251,427 | 128,270,824 | 128,265,950 | ||||||||||||||||||||||
vi
WESTLAKE CORPORATION
CONDENSED CONSOLIDATED BALANCE SHEETS
(Unaudited)
| September 30, 2026 | December 31, 2025 | |||||||||||||
(in millions of dollars) | ||||||||||||||
| ASSETS | ||||||||||||||
| Current assets | ||||||||||||||
| Cash and cash equivalents | $ | 1,764 | $ | 2,724 | ||||||||||
Available-for-sale securities | 207 | 204 | ||||||||||||
| Accounts receivable, net | 1,697 | 1,504 | ||||||||||||
| Inventories | 1,809 | 1,653 | ||||||||||||
| Prepaid expenses and other current assets | 161 | 131 | ||||||||||||
| Total current assets | 5,638 | 6,216 | ||||||||||||
| Property, plant and equipment, net | 8,604 | 8,605 | ||||||||||||
| Other assets, net | 5,033 | 5,140 | ||||||||||||
| Total assets | $ | 19,275 | $ | 19,961 | ||||||||||
| LIABILITIES AND EQUITY | ||||||||||||||
| Current liabilities (accounts payable and accrued and other liabilities) | $ | 2,370 | $ | 2,273 | ||||||||||
Current portion of long-term debt, net | — | 497 | ||||||||||||
| Long-term debt, net | 5,064 | 5,087 | ||||||||||||
| Other liabilities | 2,676 | 2,809 | ||||||||||||
| Total liabilities | 10,110 | 10,666 | ||||||||||||
| Total Westlake Corporation stockholders' equity | 8,659 | 8,792 | ||||||||||||
| Noncontrolling interests | 506 | 503 | ||||||||||||
| Total equity | 9,165 | 9,295 | ||||||||||||
| Total liabilities and equity | $ | 19,275 | $ | 19,961 | ||||||||||
vii
WESTLAKE CORPORATION
CONDENSED CONSOLIDATED STATEMENTS OF CASH FLOWS
(Unaudited)
| Nine Months Ended September 30, | ||||||||||||||
| 2026 | 2025 | |||||||||||||
(in millions of dollars) | ||||||||||||||
| Cash flows from operating activities | ||||||||||||||
| Net income (loss) | $ | 132 | $ | (938) | ||||||||||
| Adjustments to reconcile net income (loss) to net cash provided by operating activities | ||||||||||||||
| Depreciation and amortization | 860 | 881 | ||||||||||||
| Deferred income taxes | (105) | 40 | ||||||||||||
| Net loss on disposition and others | 100 | 76 | ||||||||||||
| Impairment of goodwill | — | 727 | ||||||||||||
| Other balance sheet changes | (368) | (546) | ||||||||||||
| Net cash provided by operating activities | 619 | 240 | ||||||||||||
| Cash flows from investing activities | ||||||||||||||
| Acquisitions of businesses, net of cash acquired | (171) | — | ||||||||||||
| Additions to investments in unconsolidated subsidiaries | (26) | (23) | ||||||||||||
| Additions to property, plant and equipment | (591) | (754) | ||||||||||||
| Payments for settlement of foreign currency swap agreements | (175) | — | ||||||||||||
| Proceeds from settlement of foreign currency swap agreements | 182 | — | ||||||||||||
Proceeds from maturities and paydown of available-for-sale securities | 131 | — | ||||||||||||
Purchase of available-for-sale securities | (137) | (198) | ||||||||||||
| Other, net | 8 | 7 | ||||||||||||
| Net cash used for investing activities | (779) | (968) | ||||||||||||
| Cash flows from financing activities | ||||||||||||||
| Distributions to noncontrolling interests | (32) | (33) | ||||||||||||
| Dividends paid | (205) | (204) | ||||||||||||
| Repayment of senior notes | (496) | — | ||||||||||||
| Repurchase of common stock for treasury | (30) | (30) | ||||||||||||
| Other, net | (26) | (18) | ||||||||||||
| Net cash used for financing activities | (789) | (285) | ||||||||||||
| Effect of exchange rate changes on cash, cash equivalents and restricted cash | (10) | 21 | ||||||||||||
Net decrease in cash, cash equivalents and restricted cash | (959) | (992) | ||||||||||||
| Cash, cash equivalents and restricted cash at beginning of period | 2,740 | 2,935 | ||||||||||||
| Cash, cash equivalents and restricted cash at end of period | $ | 1,781 | $ | 1,943 | ||||||||||
viii
WESTLAKE CORPORATION
SEGMENT INFORMATION
(Unaudited)
| Three Months Ended September 30, | Nine Months Ended September 30, | |||||||||||||||||||||||||
| 2026 | 2025 | 2026 | 2025 | |||||||||||||||||||||||
(in millions of dollars) | ||||||||||||||||||||||||||
| Net external sales | ||||||||||||||||||||||||||
| Housing and Infrastructure Products | ||||||||||||||||||||||||||
| Housing Products | $ | 846 | $ | 928 | $ | 2,645 | $ | 2,746 | ||||||||||||||||||
| Infrastructure Products | 241 | 163 | 687 | 501 | ||||||||||||||||||||||
| Total Housing and Infrastructure Products | 1,087 | 1,091 | 3,332 | 3,247 | ||||||||||||||||||||||
| Performance and Essential Materials | ||||||||||||||||||||||||||
| Performance Materials | 1,176 | 1,010 | 3,415 | 3,088 | ||||||||||||||||||||||
| Essential Materials | 718 | 737 | 2,157 | 2,302 | ||||||||||||||||||||||
| Total Performance and Essential Materials | 1,894 | 1,747 | 5,572 | 5,390 | ||||||||||||||||||||||
Total reportable segments and consolidated | $ | 2,981 | $ | 2,838 | $ | 8,904 | $ | 8,637 | ||||||||||||||||||
| Income (loss) from operations | ||||||||||||||||||||||||||
Housing and Infrastructure Products | $ | 128 | $ | 151 | $ | 396 | $ | 521 | ||||||||||||||||||
| Performance and Essential Materials | (64) | (902) | (90) | (1,383) | ||||||||||||||||||||||
| Total reportable segments | 64 | (751) | 306 | (862) | ||||||||||||||||||||||
| Corporate and other | (21) | (15) | (71) | (45) | ||||||||||||||||||||||
| Consolidated | $ | 43 | $ | (766) | $ | 235 | $ | (907) | ||||||||||||||||||
| Depreciation and amortization | ||||||||||||||||||||||||||
Housing and Infrastructure Products | $ | 63 | $ | 62 | $ | 185 | $ | 170 | ||||||||||||||||||
| Performance and Essential Materials | 224 | 238 | 667 | 701 | ||||||||||||||||||||||
| Total reportable segments | 287 | 300 | 852 | 871 | ||||||||||||||||||||||
| Corporate and other | 3 | 3 | 8 | 10 | ||||||||||||||||||||||
| Consolidated | $ | 290 | $ | 303 | $ | 860 | $ | 881 | ||||||||||||||||||
| Other income (loss), net | ||||||||||||||||||||||||||
Housing and Infrastructure Products | $ | 4 | $ | 2 | $ | 8 | $ | 2 | ||||||||||||||||||
| Performance and Essential Materials | (1) | 10 | 17 | 23 | ||||||||||||||||||||||
| Total reportable segments | 3 | 12 | 25 | 25 | ||||||||||||||||||||||
| Corporate and other | 14 | 20 | 59 | 68 | ||||||||||||||||||||||
| Consolidated | $ | 17 | $ | 32 | $ | 84 | $ | 93 | ||||||||||||||||||
ix
WESTLAKE CORPORATION
RECONCILIATION OF EBITDA TO NET INCOME (LOSS), INCOME (LOSS) FROM OPERATIONS AND
NET CASH PROVIDED BY OPERATING ACTIVITIES (INCLUDING AND EXCLUDING IDENTIFIED ITEMS)
(Unaudited)
| Three Months Ended June 30, | Three Months Ended September 30, | Nine Months Ended September 30, | ||||||||||||||||||||||||||||||
| 2026 | 2026 | 2025 | 2026 | 2025 | ||||||||||||||||||||||||||||
(in millions of dollars, except percentages) | ||||||||||||||||||||||||||||||||
| Net cash provided by operating activities | $ | 305 | $ | 408 | $ | 182 | $ | 619 | $ | 240 | ||||||||||||||||||||||
| Changes in operating assets and liabilities and other | (54) | (509) | (895) | (592) | (1,138) | |||||||||||||||||||||||||||
| Deferred income taxes | 20 | 119 | (59) | 105 | (40) | |||||||||||||||||||||||||||
| Net income (loss) | 271 | 18 | (772) | 132 | (938) | |||||||||||||||||||||||||||
| Add: | ||||||||||||||||||||||||||||||||
Identified Items, after-tax | — | 52 | 744 | 121 | 881 | |||||||||||||||||||||||||||
| Net income (loss) excl. Identified Items | $ | 271 | $ | 70 | $ | (28) | $ | 253 | $ | (57) | ||||||||||||||||||||||
| Net income (loss) | 271 | 18 | (772) | 132 | (938) | |||||||||||||||||||||||||||
| Less: | ||||||||||||||||||||||||||||||||
Other income, net | 29 | 17 | 32 | 84 | 93 | |||||||||||||||||||||||||||
| Interest expense | (55) | (52) | (41) | (163) | (120) | |||||||||||||||||||||||||||
| Benefit from (provision for) income taxes | (67) | 10 | 3 | (24) | (4) | |||||||||||||||||||||||||||
| Income (loss) from operations | 364 | 43 | (766) | 235 | (907) | |||||||||||||||||||||||||||
| Add: | ||||||||||||||||||||||||||||||||
Identified Items, pre-tax | — | 58 | 744 | 143 | 881 | |||||||||||||||||||||||||||
| Income (loss) from operations excl. Identified Items | 364 | 101 | (22) | 378 | (26) | |||||||||||||||||||||||||||
| Add: | ||||||||||||||||||||||||||||||||
| Depreciation and amortization | 286 | 290 | 303 | 860 | 881 | |||||||||||||||||||||||||||
| Other income, net | 29 | 17 | 32 | 84 | 93 | |||||||||||||||||||||||||||
EBITDA excl. Identified Items | 679 | 408 | 313 | 1,322 | 948 | |||||||||||||||||||||||||||
| Less: | ||||||||||||||||||||||||||||||||
Identified Items, pre-tax | — | 58 | 744 | 143 | 881 | |||||||||||||||||||||||||||
| EBITDA | $ | 679 | $ | 350 | $ | (431) | $ | 1,179 | $ | 67 | ||||||||||||||||||||||
| Net external sales | $ | 3,271 | $ | 2,981 | $ | 2,838 | $ | 8,904 | $ | 8,637 | ||||||||||||||||||||||
| Operating income (loss) margin | 11% | 1% | (27)% | 3% | (11)% | |||||||||||||||||||||||||||
| Operating income (loss) margin excl. Identified Items | 11% | 3% | (1)% | 4% | —% | |||||||||||||||||||||||||||
EBITDA margin | 21% | 12% | (15)% | 13% | 1% | |||||||||||||||||||||||||||
EBITDA margin excl. Identified Items | 21% | 14% | 11% | 15% | 11% | |||||||||||||||||||||||||||
x
WESTLAKE CORPORATION
RECONCILIATION OF DILUTED EARNINGS (LOSS) PER COMMON SHARE TO DILUTED EARNINGS (LOSS) PER COMMON SHARE EXCLUDING IDENTIFIED ITEMS
(Unaudited)
| Three Months Ended June 30, | Three Months Ended September 30, | Nine Months Ended September 30, | ||||||||||||||||||||||||||||||
| 2026 | 2026 | 2025 | 2026 | 2025 | ||||||||||||||||||||||||||||
(per share data) | ||||||||||||||||||||||||||||||||
Diluted earnings (loss) per common share attributable to Westlake Corporation | $ | 2.01 | $ | 0.05 | $ | (6.06) | $ | 0.75 | $ | (7.48) | ||||||||||||||||||||||
| Add: | ||||||||||||||||||||||||||||||||
Loss per common share relating to Identified Items | — | 0.40 | 5.77 | 0.94 | 6.84 | |||||||||||||||||||||||||||
Diluted earnings (loss) per common share attributable to Westlake Corporation excl. Identified Items | $ | 2.01 | $ | 0.45 | $ | (0.29) | $ | 1.69 | $ | (0.64) | ||||||||||||||||||||||
WESTLAKE CORPORATION
RECONCILIATION OF FREE CASH FLOW TO NET CASH PROVIDED BY OPERATING ACTIVITIES
(Unaudited)
| Three Months Ended June 30, | Three Months Ended September 30, | Nine Months Ended September 30, | ||||||||||||||||||||||||||||||
| 2026 | 2026 | 2025 | 2026 | 2025 | ||||||||||||||||||||||||||||
(in millions of dollars) | ||||||||||||||||||||||||||||||||
| Net cash provided by operating activities | $ | 305 | $ | 408 | $ | 182 | $ | 619 | $ | 240 | ||||||||||||||||||||||
| Less: | ||||||||||||||||||||||||||||||||
| Additions to property, plant and equipment | 194 | 188 | 239 | 591 | 754 | |||||||||||||||||||||||||||
| Free cash flow | $ | 111 | $ | 220 | $ | (57) | $ | 28 | $ | (514) | ||||||||||||||||||||||
xi
WESTLAKE CORPORATION
RECONCILIATION OF HIP SEGMENT EBITDA TO INCOME FROM OPERATIONS (INCLUDING AND EXCLUDING IDENTIFIED ITEMS)
(Unaudited)
| Three Months Ended June 30, | Three Months Ended September 30, | Nine Months Ended September 30, | ||||||||||||||||||||||||||||||
| 2026 | 2026 | 2025 | 2026 | 2025 | ||||||||||||||||||||||||||||
(in millions of dollars, except percentages) | ||||||||||||||||||||||||||||||||
| Housing and Infrastructure Products Segment | ||||||||||||||||||||||||||||||||
Income from operations | $ | 212 | $ | 128 | $ | 151 | $ | 396 | $ | 521 | ||||||||||||||||||||||
Add: | ||||||||||||||||||||||||||||||||
Identified Items | — | — | — | 68 | — | |||||||||||||||||||||||||||
| Income from operations excl. Identified Items | 212 | 128 | 151 | 464 | 521 | |||||||||||||||||||||||||||
| Add: | ||||||||||||||||||||||||||||||||
| Depreciation and amortization | 62 | 63 | 62 | 185 | 170 | |||||||||||||||||||||||||||
| Other income, net | 2 | 4 | 2 | 8 | 2 | |||||||||||||||||||||||||||
| EBITDA excl. Identified Items | 276 | 195 | 215 | 657 | 693 | |||||||||||||||||||||||||||
Less: | ||||||||||||||||||||||||||||||||
| Identified Items | — | — | — | 68 | — | |||||||||||||||||||||||||||
| EBITDA | $ | 276 | $ | 195 | $ | 215 | $ | 589 | $ | 693 | ||||||||||||||||||||||
| Net external sales | $ | 1,252 | $ | 1,087 | $ | 1,091 | $ | 3,332 | $ | 3,247 | ||||||||||||||||||||||
Operating income margin | 17% | 12% | 14% | 12% | 16% | |||||||||||||||||||||||||||
| Operating income margin excl. Identified Items | 17% | 12% | 14% | 14% | 16% | |||||||||||||||||||||||||||
| EBITDA margin | 22% | 18% | 20% | 18% | 21% | |||||||||||||||||||||||||||
| EBITDA margin excl. Identified Items | 22% | 18% | 20% | 20% | 21% | |||||||||||||||||||||||||||
xii
WESTLAKE CORPORATION
RECONCILIATION OF PEM SEGMENT EBITDA TO INCOME (LOSS) FROM OPERATIONS (INCLUDING AND EXCLUDING IDENTIFIED ITEMS)
(Unaudited)
| Three Months Ended June 30, | Three Months Ended September 30, | Nine Months Ended September 30, | ||||||||||||||||||||||||||||||
| 2026 | 2026 | 2025 | 2026 | 2025 | ||||||||||||||||||||||||||||
(in millions of dollars, except percentages) | ||||||||||||||||||||||||||||||||
| Performance and Essential Materials Segment | ||||||||||||||||||||||||||||||||
Income (loss) from operations | $ | 185 | $ | (64) | $ | (902) | $ | (90) | $ | (1,383) | ||||||||||||||||||||||
| Add: | ||||||||||||||||||||||||||||||||
| Identified Items | — | 56 | 744 | 73 | 881 | |||||||||||||||||||||||||||
Income (loss) from operations excl. Identified Items | 185 | (8) | (158) | (17) | (502) | |||||||||||||||||||||||||||
| Add: | ||||||||||||||||||||||||||||||||
| Depreciation and amortization | 222 | 224 | 238 | 667 | 701 | |||||||||||||||||||||||||||
| Other income (loss), net | 9 | (1) | 10 | 17 | 23 | |||||||||||||||||||||||||||
EBITDA excl. Identified Items | 416 | 215 | 90 | 667 | 222 | |||||||||||||||||||||||||||
| Less: | ||||||||||||||||||||||||||||||||
| Identified Items | — | 56 | 744 | 73 | 881 | |||||||||||||||||||||||||||
EBITDA | $ | 416 | $ | 159 | $ | (654) | $ | 594 | $ | (659) | ||||||||||||||||||||||
| Net external sales | $ | 2,019 | $ | 1,894 | $ | 1,747 | $ | 5,572 | $ | 5,390 | ||||||||||||||||||||||
| Operating income (loss) margin | 9% | (3)% | (52)% | (2)% | (26)% | |||||||||||||||||||||||||||
| Operating income (loss) margin excl. Identified Items | 9% | —% | (9)% | —% | (9)% | |||||||||||||||||||||||||||
EBITDA margin | 21% | 8% | (37)% | 11% | (12)% | |||||||||||||||||||||||||||
EBITDA margin excl. Identified Items | 21% | 11% | 5% | 12% | 4% | |||||||||||||||||||||||||||
xiii
WESTLAKE CORPORATION
SUPPLEMENTAL INFORMATION
PRODUCT SALES PRICE AND VOLUME VARIANCE BY OPERATING SEGMENTS
(Unaudited)
| Third Quarter 2026 vs. Third Quarter 2025 | Third Quarter 2026 vs. Second Quarter 2026 | |||||||||||||||||||||||||
| Average Sales Price | Volume | Average Sales Price | Volume | |||||||||||||||||||||||
| Housing and Infrastructure Products | +1 | % | -2 | % | +4 | % | -17 | % | ||||||||||||||||||
| Performance and Essential Materials | +9 | % | -1 | % | -8 | % | +2 | % | ||||||||||||||||||
| Company | +6 | % | -1 | % | -4 | % | -5 | % | ||||||||||||||||||
WESTLAKE CORPORATION
SUPPLEMENTAL INFORMATION
PRODUCT SALES PRICE AND VOLUME VARIANCE BY OPERATING SEGMENTS - EXCLUDING PLANT CLOSURES AND ACQUISITION (1)
(Unaudited)
| Third Quarter 2026 vs. Third Quarter 2025 | Third Quarter 2026 vs. Second Quarter 2026 | |||||||||||||||||||||||||
| Average Sales Price | Volume | Average Sales Price | Volume | |||||||||||||||||||||||
| Housing and Infrastructure Products | +1 | % | -6 | % | +4 | % | -17 | % | ||||||||||||||||||
| Performance and Essential Materials | +9 | % | +4 | % | -8 | % | — | % | ||||||||||||||||||
| Company | +6 | % | — | % | -4 | % | -7 | % | ||||||||||||||||||
______________________________
(1)Adjustments include:
a.Excludes sales in the comparative periods related to certain of the Company's North America Chlorovinyls production facilities, including (i) its polyvinyl chloride plant at the Aberdeen, Mississippi facility, (ii) its vinyl chloride monomer plant at the Lake Charles, Louisiana North facility, and (iii) one of its diaphragm chlor-alkali units at the Lake Charles, Louisiana South facility, and the Company's styrene production plant located at the Lake Charles, Louisiana facilities, each of which ceased operations in December 2025.
b.The third quarter of 2026 comparison to the third quarter of 2025 excludes sales related to ACI, which was acquired by the Company in January 2026.
c.Excludes sales related to the Wilhelmshaven vinyls facility, which was acquired by the Company in June 2026.
xiv
1 Earnings Presentation 3Q 2026
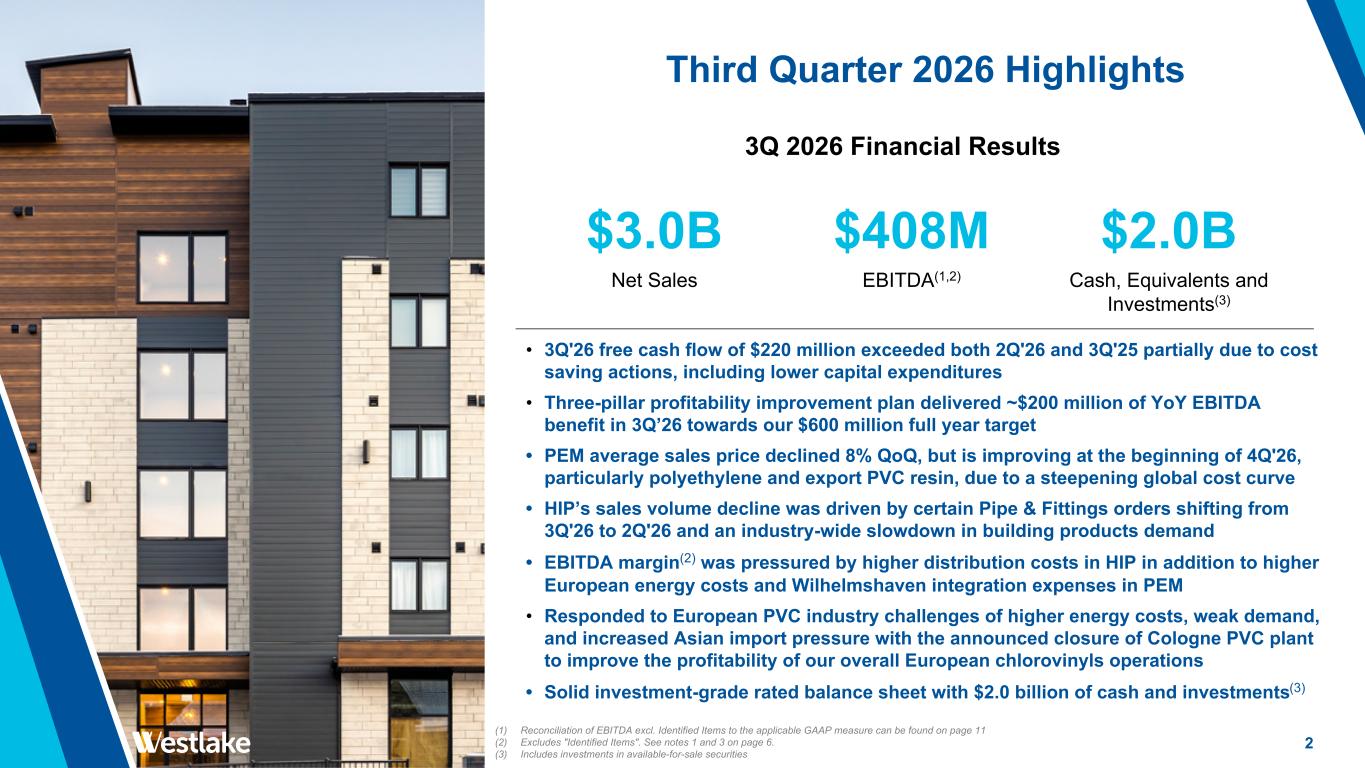
2 Third Quarter 2026 Highlights • 3Q'26 free cash flow of $220 million exceeded both 2Q'26 and 3Q'25 partially due to cost saving actions, including lower capital expenditures • Three-pillar profitability improvement plan delivered ~$200 million of YoY EBITDA benefit in 3Q’26 towards our $600 million full year target • PEM average sales price declined 8% QoQ, but is improving at the beginning of 4Q'26, particularly polyethylene and export PVC resin, due to a steepening global cost curve • HIP’s sales volume decline was driven by certain Pipe & Fittings orders shifting from 3Q'26 to 2Q'26 and an industry-wide slowdown in building products demand • EBITDA margin(2) was pressured by higher distribution costs in HIP in addition to higher European energy costs and Wilhelmshaven integration expenses in PEM • Responded to European PVC industry challenges of higher energy costs, weak demand, and increased Asian import pressure with the announced closure of Cologne PVC plant to improve the profitability of our overall European chlorovinyls operations • Solid investment-grade rated balance sheet with $2.0 billion of cash and investments(3) (1) Reconciliation of EBITDA excl. Identified Items to the applicable GAAP measure can be found on page 11 (2) Excludes "Identified Items". See notes 1 and 3 on page 6. (3) Includes investments in available-for-sale securities 3Q 2026 Financial Results $408M EBITDA(1,2) $3.0B Net Sales $2.0B Cash, Equivalents and Investments(3)
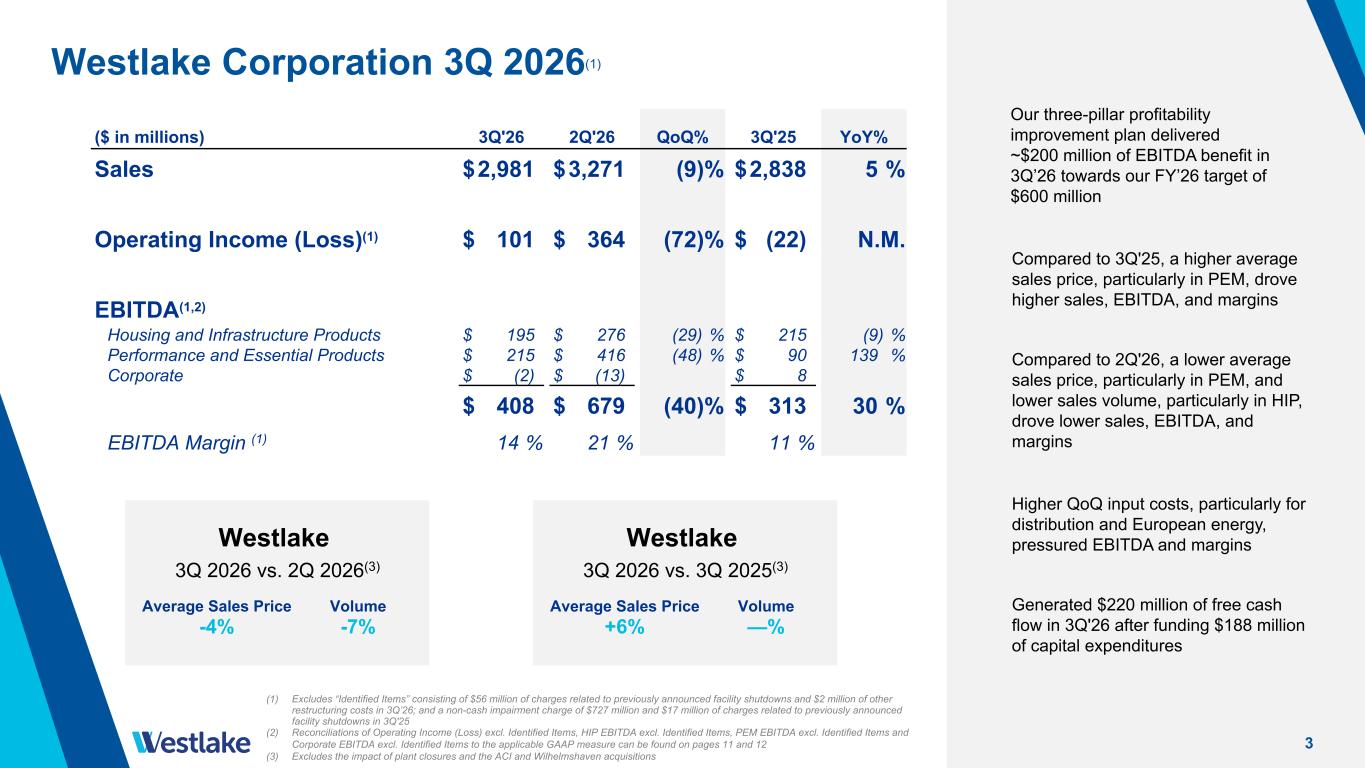
3 Westlake Corporation 3Q 2026(1) Westlake 3Q 2026 vs. 2Q 2026(3) Average Sales Price -4% Volume -7% Westlake 3Q 2026 vs. 3Q 2025(3) Average Sales Price +6% Volume —% (1) Excludes “Identified Items” consisting of $56 million of charges related to previously announced facility shutdowns and $2 million of other restructuring costs in 3Q’26; and a non-cash impairment charge of $727 million and $17 million of charges related to previously announced facility shutdowns in 3Q'25 (2) Reconciliations of Operating Income (Loss) excl. Identified Items, HIP EBITDA excl. Identified Items, PEM EBITDA excl. Identified Items and Corporate EBITDA excl. Identified Items to the applicable GAAP measure can be found on pages 11 and 12 (3) Excludes the impact of plant closures and the ACI and Wilhelmshaven acquisitions Our three-pillar profitability improvement plan delivered ~$200 million of EBITDA benefit in 3Q’26 towards our FY’26 target of $600 million Generated $220 million of free cash flow in 3Q'26 after funding $188 million of capital expenditures Compared to 2Q'26, a lower average sales price, particularly in PEM, and lower sales volume, particularly in HIP, drove lower sales, EBITDA, and margins ($ in millions) 3Q'26 2Q'26 QoQ% 3Q'25 YoY% Sales $ 2,981 $ 3,271 (9) % $ 2,838 5 % Operating Income (Loss)(1) $ 101 $ 364 (72) % $ (22) N.M. EBITDA(1,2) Housing and Infrastructure Products $ 195 $ 276 (29) % $ 215 (9) % Performance and Essential Products $ 215 $ 416 (48) % $ 90 139 % Corporate $ (2) $ (13) $ 8 $ 408 $ 679 (40) % $ 313 30 % EBITDA Margin (1) 14 % 21 % 11 % Higher QoQ input costs, particularly for distribution and European energy, pressured EBITDA and margins Compared to 3Q'25, a higher average sales price, particularly in PEM, drove higher sales, EBITDA, and margins
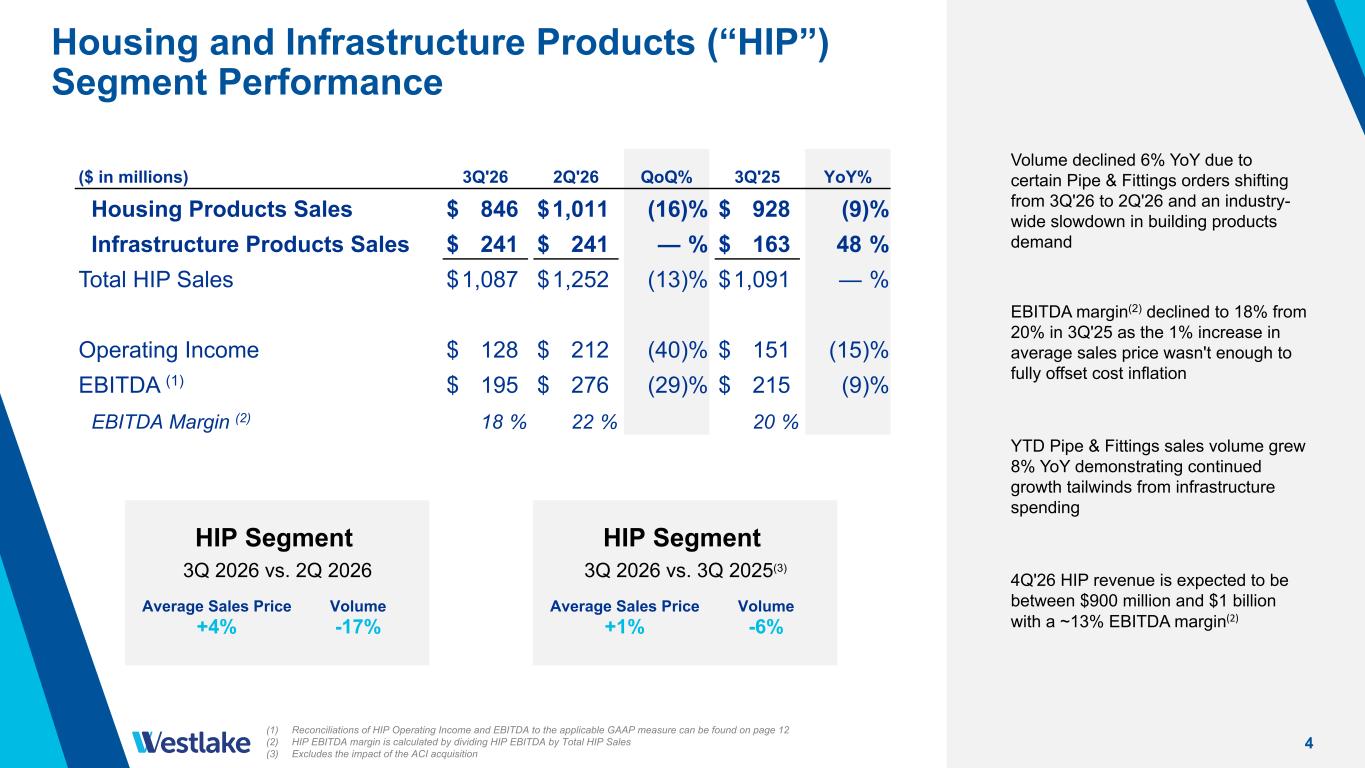
4 Housing and Infrastructure Products (“HIP”) Segment Performance HIP Segment 3Q 2026 vs. 2Q 2026 Average Sales Price +4% Volume -17% HIP Segment 3Q 2026 vs. 3Q 2025(3) Average Sales Price +1% Volume -6% YTD Pipe & Fittings sales volume grew 8% YoY demonstrating continued growth tailwinds from infrastructure spending (1) Reconciliations of HIP Operating Income and EBITDA to the applicable GAAP measure can be found on page 12 (2) HIP EBITDA margin is calculated by dividing HIP EBITDA by Total HIP Sales (3) Excludes the impact of the ACI acquisition Volume declined 6% YoY due to certain Pipe & Fittings orders shifting from 3Q'26 to 2Q'26 and an industry- wide slowdown in building products demand 4Q'26 HIP revenue is expected to be between $900 million and $1 billion with a ~13% EBITDA margin(2) EBITDA margin(2) declined to 18% from 20% in 3Q'25 as the 1% increase in average sales price wasn't enough to fully offset cost inflation ($ in millions) 3Q'26 2Q'26 QoQ% 3Q'25 YoY% Housing Products Sales $ 846 $ 1,011 (16) % $ 928 (9) % Infrastructure Products Sales $ 241 $ 241 — % $ 163 48 % Total HIP Sales $ 1,087 $ 1,252 (13) % $ 1,091 — % Operating Income $ 128 $ 212 (40) % $ 151 (15) % EBITDA (1) $ 195 $ 276 (29) % $ 215 (9) % EBITDA Margin (2) 18 % 22 % 20 %
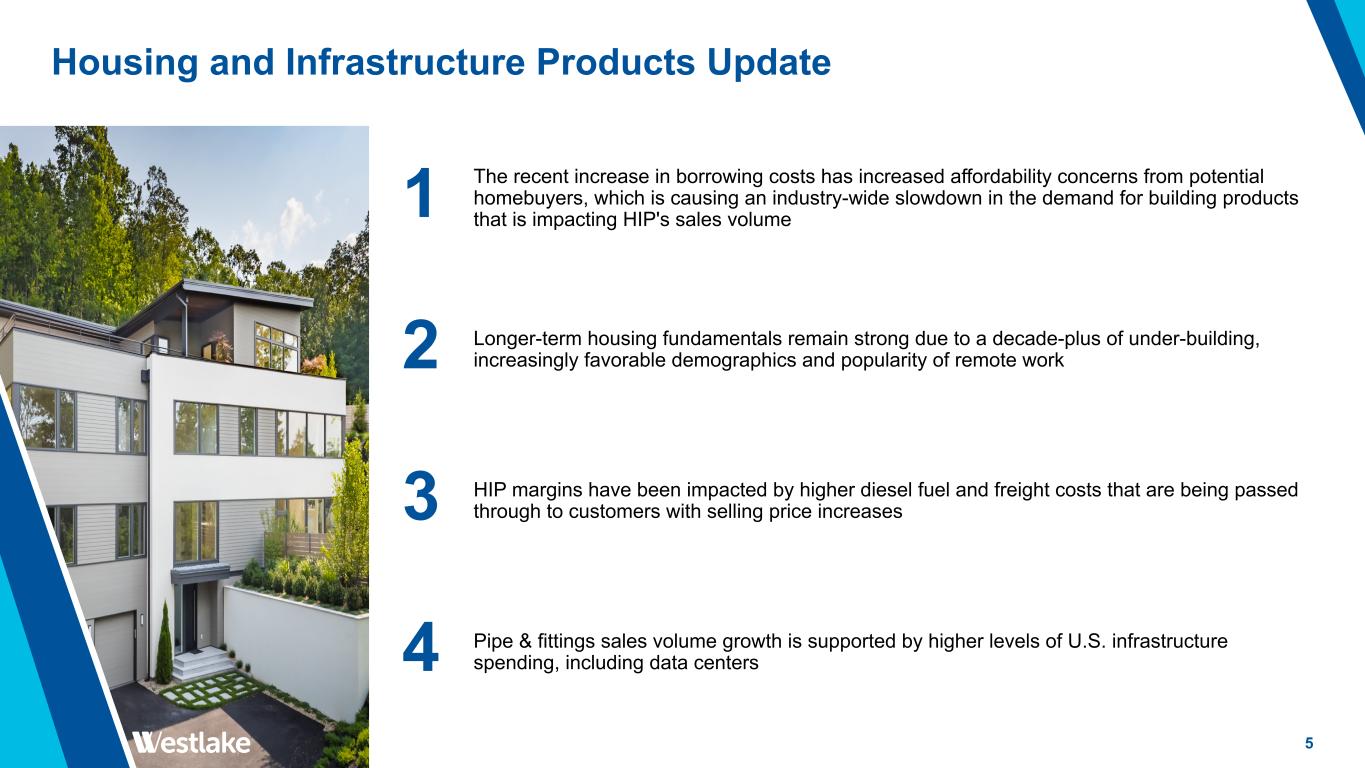
5 Housing and Infrastructure Products Update 2 Longer-term housing fundamentals remain strong due to a decade-plus of under-building, increasingly favorable demographics and popularity of remote work 3 HIP margins have been impacted by higher diesel fuel and freight costs that are being passed through to customers with selling price increases 4 Pipe & fittings sales volume growth is supported by higher levels of U.S. infrastructure spending, including data centers 1 The recent increase in borrowing costs has increased affordability concerns from potential homebuyers, which is causing an industry-wide slowdown in the demand for building products that is impacting HIP's sales volume
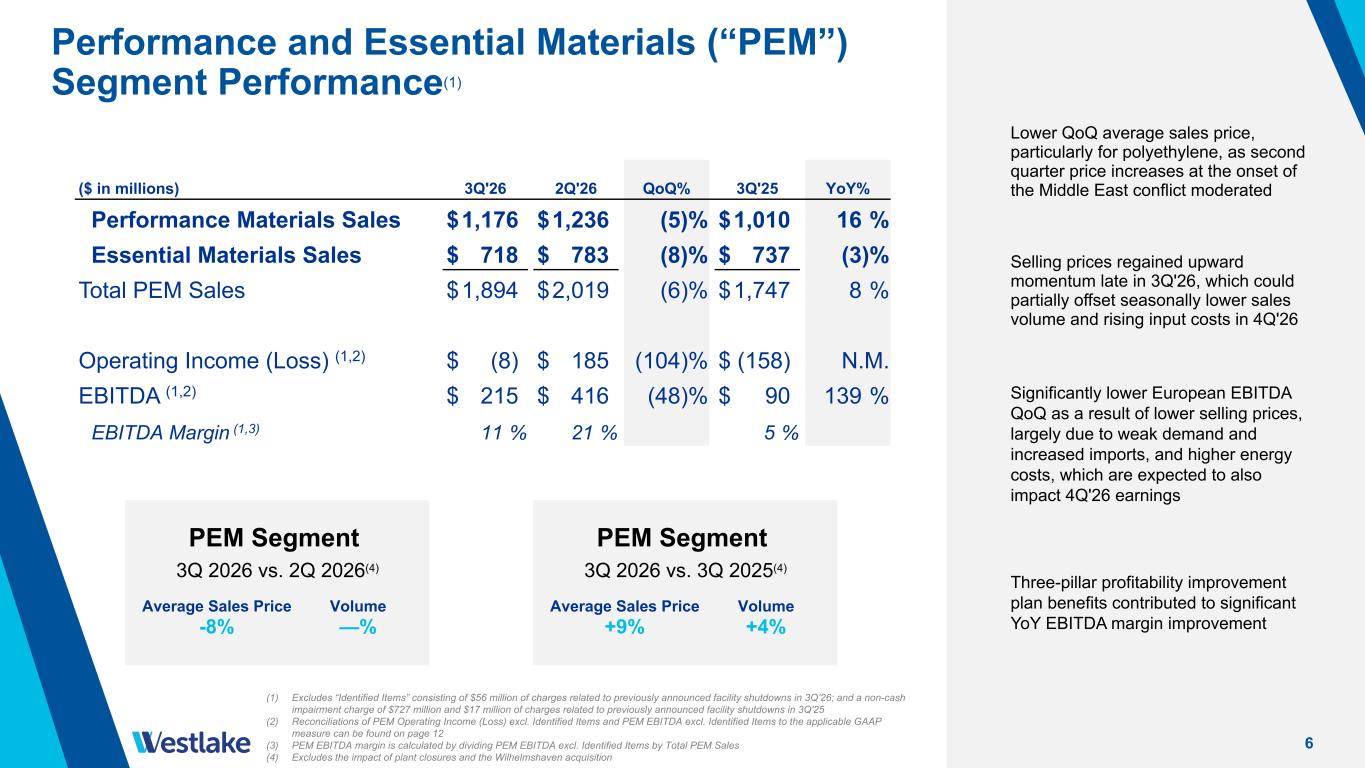
6 PEM Segment 3Q 2026 vs. 2Q 2026(4) Average Sales Price -8% Volume —% PEM Segment 3Q 2026 vs. 3Q 2025(4) Average Sales Price +9% Volume +4% Significantly lower European EBITDA QoQ as a result of lower selling prices, largely due to weak demand and increased imports, and higher energy costs, which are expected to also impact 4Q'26 earnings Lower QoQ average sales price, particularly for polyethylene, as second quarter price increases at the onset of the Middle East conflict moderated (1) Excludes “Identified Items” consisting of $56 million of charges related to previously announced facility shutdowns in 3Q’26; and a non-cash impairment charge of $727 million and $17 million of charges related to previously announced facility shutdowns in 3Q'25 (2) Reconciliations of PEM Operating Income (Loss) excl. Identified Items and PEM EBITDA excl. Identified Items to the applicable GAAP measure can be found on page 12 (3) PEM EBITDA margin is calculated by dividing PEM EBITDA excl. Identified Items by Total PEM Sales (4) Excludes the impact of plant closures and the Wilhelmshaven acquisition Performance and Essential Materials (“PEM”) Segment Performance(1) Three-pillar profitability improvement plan benefits contributed to significant YoY EBITDA margin improvement ($ in millions) 3Q'26 2Q'26 QoQ% 3Q'25 YoY% Performance Materials Sales $ 1,176 $ 1,236 (5) % $ 1,010 16 % Essential Materials Sales $ 718 $ 783 (8) % $ 737 (3) % Total PEM Sales $ 1,894 $ 2,019 (6) % $ 1,747 8 % Operating Income (Loss) (1,2) $ (8) $ 185 (104) % $ (158) N.M. EBITDA (1,2) $ 215 $ 416 (48) % $ 90 139 % EBITDA Margin (1,3) 11 % 21 % 5 % Selling prices regained upward momentum late in 3Q'26, which could partially offset seasonally lower sales volume and rising input costs in 4Q'26
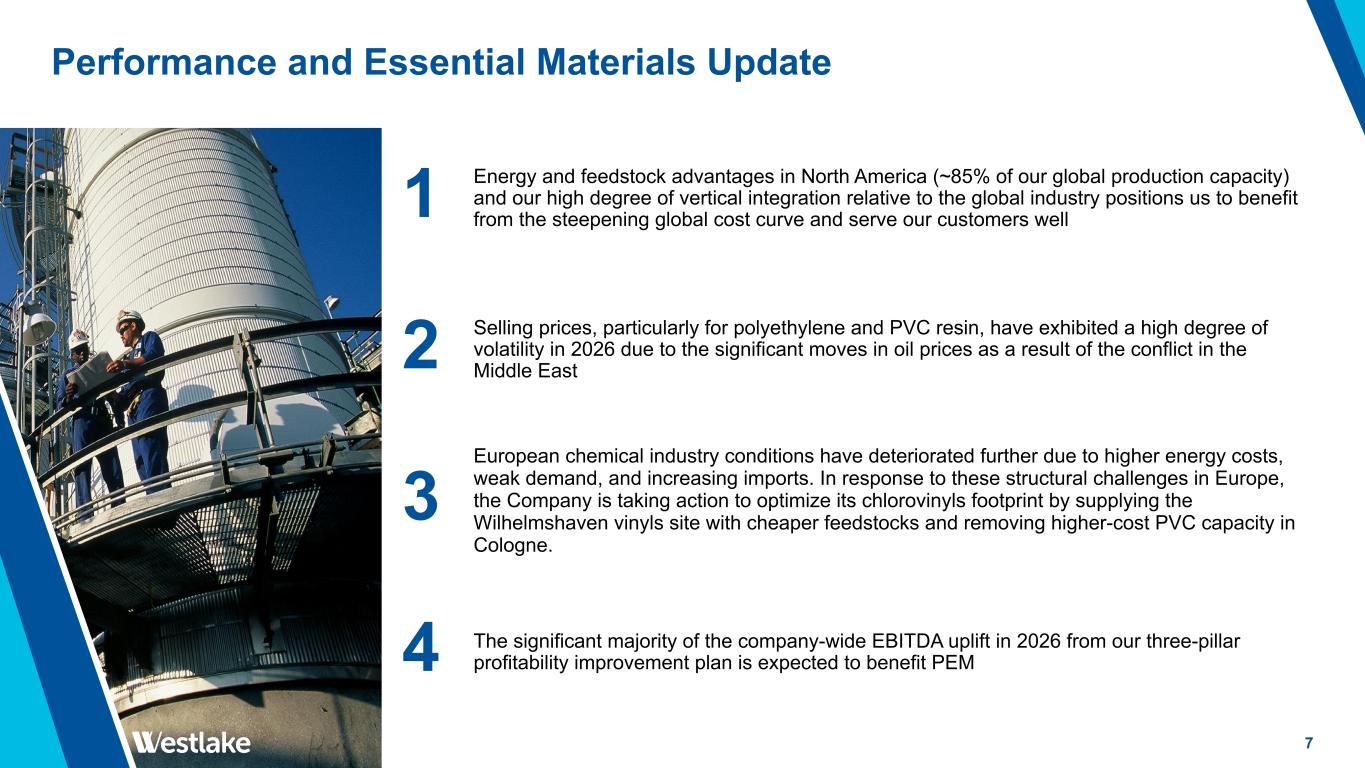
7 Performance and Essential Materials Update 2 Selling prices, particularly for polyethylene and PVC resin, have exhibited a high degree of volatility in 2026 due to the significant moves in oil prices as a result of the conflict in the Middle East 3 European chemical industry conditions have deteriorated further due to higher energy costs, weak demand, and increasing imports. In response to these structural challenges in Europe, the Company is taking action to optimize its chlorovinyls footprint by supplying the Wilhelmshaven vinyls site with cheaper feedstocks and removing higher-cost PVC capacity in Cologne. 4 The significant majority of the company-wide EBITDA uplift in 2026 from our three-pillar profitability improvement plan is expected to benefit PEM 1 Energy and feedstock advantages in North America (~85% of our global production capacity) and our high degree of vertical integration relative to the global industry positions us to benefit from the steepening global cost curve and serve our customers well
8 Financial Reconciliations
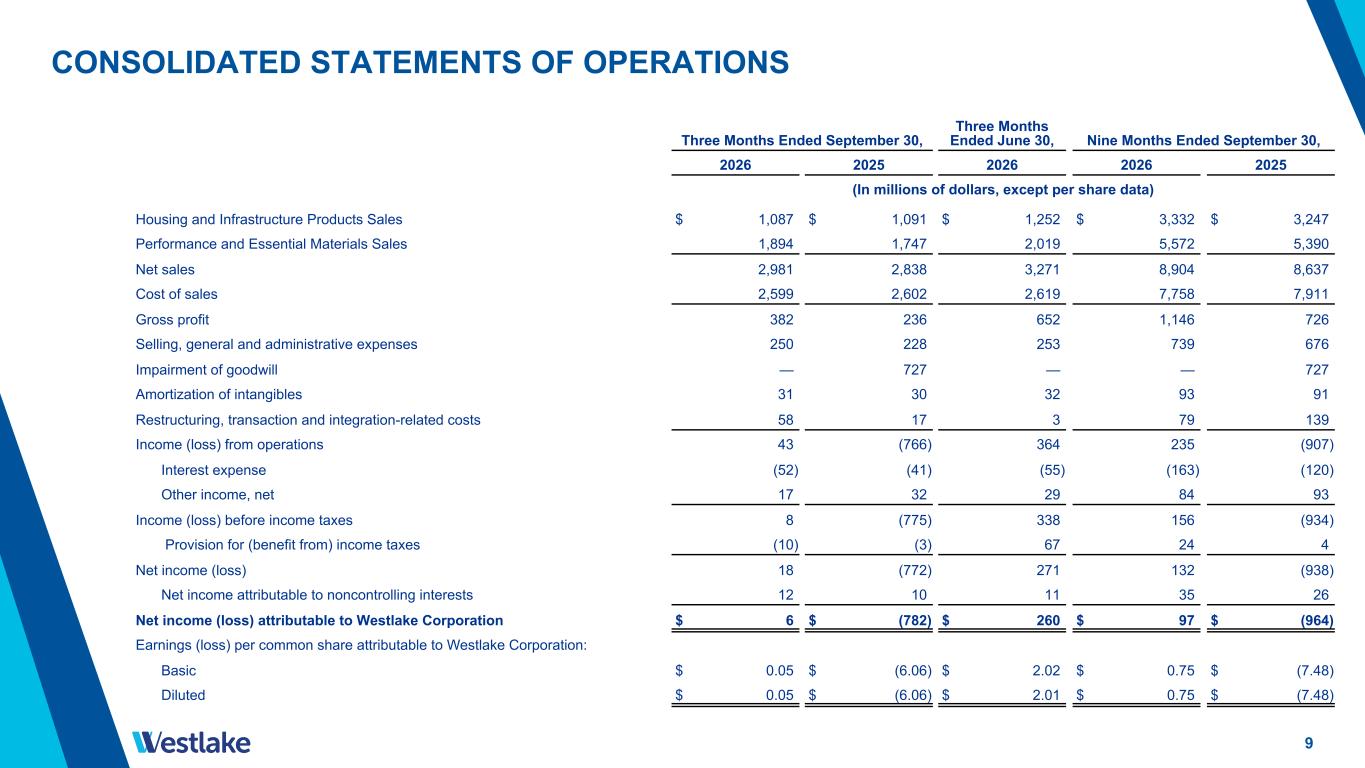
9 CONSOLIDATED STATEMENTS OF OPERATIONS Three Months Ended September 30, Three Months Ended June 30, Nine Months Ended September 30, 2026 2025 2026 2026 2025 (In millions of dollars, except per share data) Housing and Infrastructure Products Sales $ 1,087 $ 1,091 $ 1,252 $ 3,332 $ 3,247 Performance and Essential Materials Sales 1,894 1,747 2,019 5,572 5,390 Net sales 2,981 2,838 3,271 8,904 8,637 Cost of sales 2,599 2,602 2,619 7,758 7,911 Gross profit 382 236 652 1,146 726 Selling, general and administrative expenses 250 228 253 739 676 Impairment of goodwill — 727 — — 727 Amortization of intangibles 31 30 32 93 91 Restructuring, transaction and integration-related costs 58 17 3 79 139 Income (loss) from operations 43 (766) 364 235 (907) Interest expense (52) (41) (55) (163) (120) Other income, net 17 32 29 84 93 Income (loss) before income taxes 8 (775) 338 156 (934) Provision for (benefit from) income taxes (10) (3) 67 24 4 Net income (loss) 18 (772) 271 132 (938) Net income attributable to noncontrolling interests 12 10 11 35 26 Net income (loss) attributable to Westlake Corporation $ 6 $ (782) $ 260 $ 97 $ (964) Earnings (loss) per common share attributable to Westlake Corporation: Basic $ 0.05 $ (6.06) $ 2.02 $ 0.75 $ (7.48) Diluted $ 0.05 $ (6.06) $ 2.01 $ 0.75 $ (7.48)
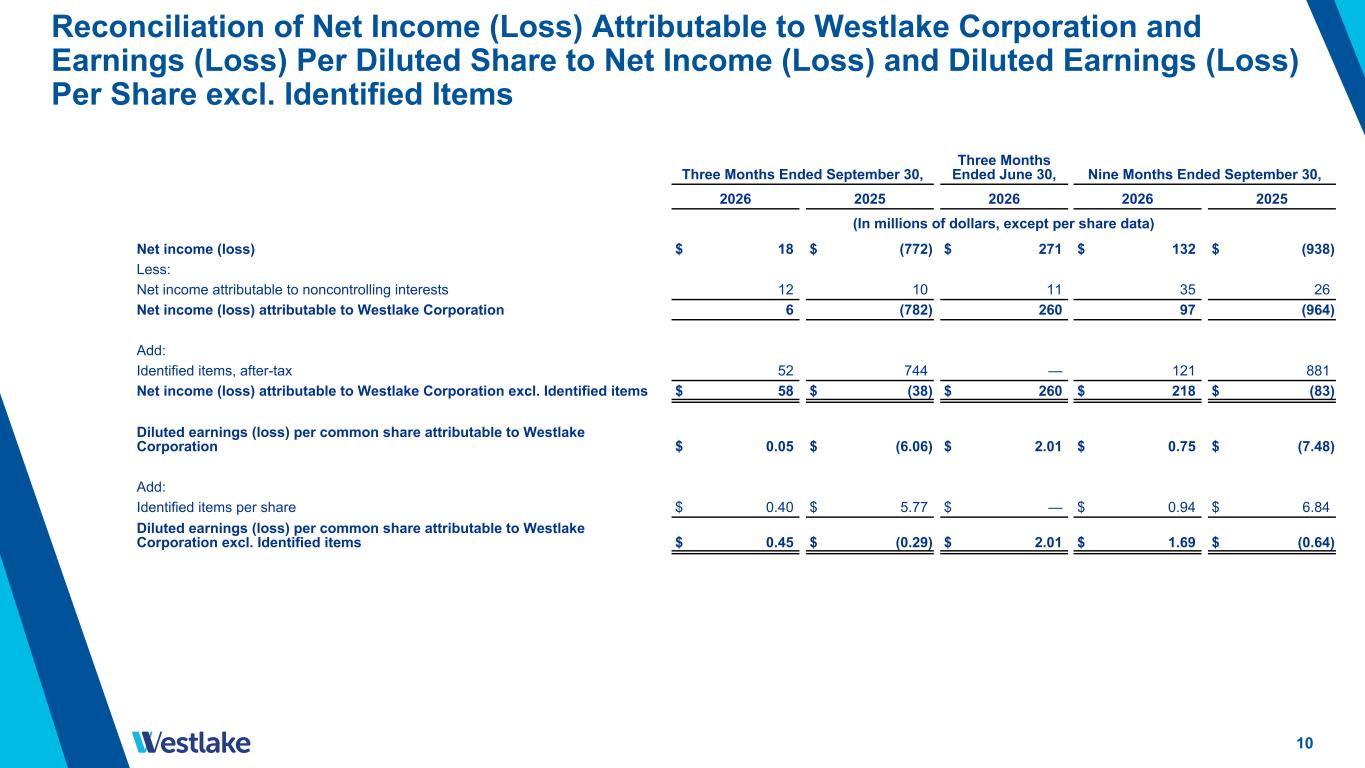
10 Reconciliation of Net Income (Loss) Attributable to Westlake Corporation and Earnings (Loss) Per Diluted Share to Net Income (Loss) and Diluted Earnings (Loss) Per Share excl. Identified Items Three Months Ended September 30, Three Months Ended June 30, Nine Months Ended September 30, 2026 2025 2026 2026 2025 (In millions of dollars, except per share data) Net income (loss) $ 18 $ (772) $ 271 $ 132 $ (938) Less: Net income attributable to noncontrolling interests 12 10 11 35 26 Net income (loss) attributable to Westlake Corporation 6 (782) 260 97 (964) Add: Identified items, after-tax 52 744 — 121 881 Net income (loss) attributable to Westlake Corporation excl. Identified items $ 58 $ (38) $ 260 $ 218 $ (83) Diluted earnings (loss) per common share attributable to Westlake Corporation $ 0.05 $ (6.06) $ 2.01 $ 0.75 $ (7.48) Add: Identified items per share $ 0.40 $ 5.77 $ — $ 0.94 $ 6.84 Diluted earnings (loss) per common share attributable to Westlake Corporation excl. Identified items $ 0.45 $ (0.29) $ 2.01 $ 1.69 $ (0.64)
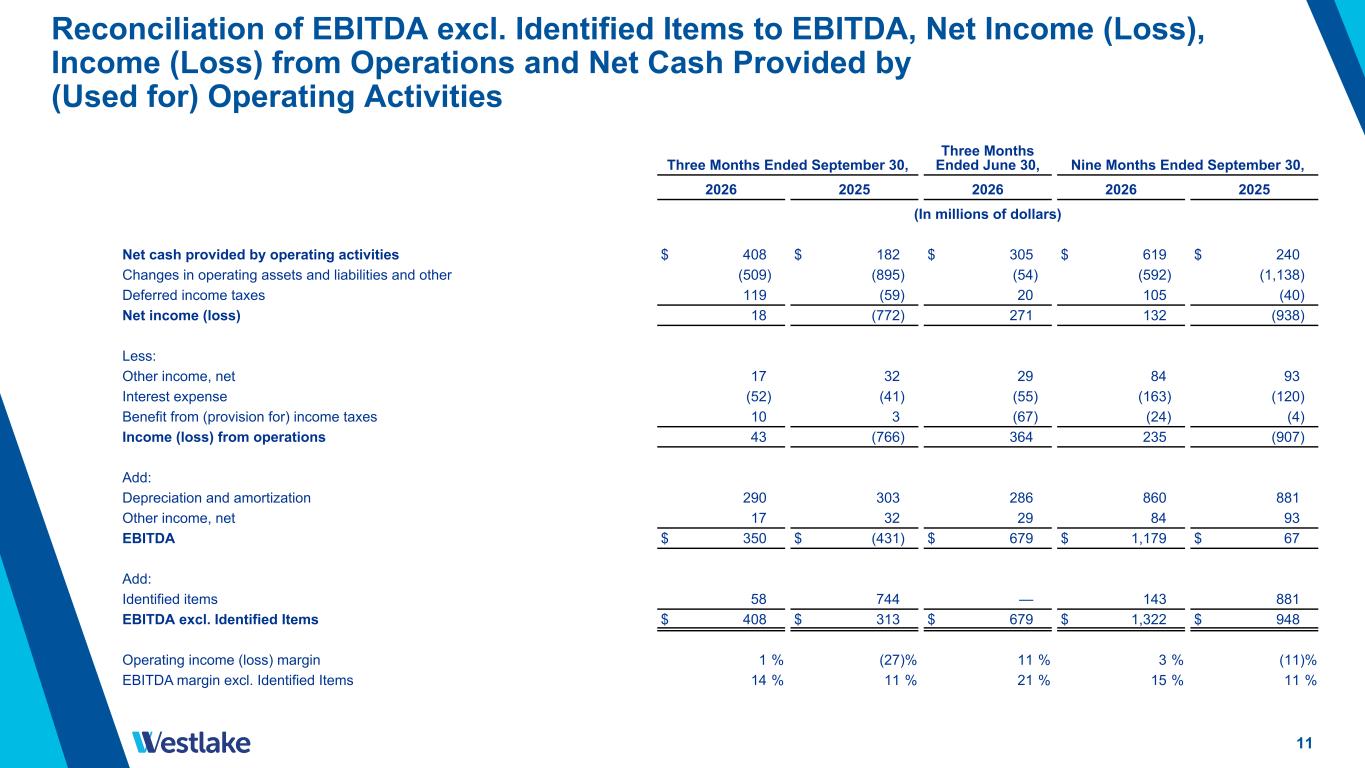
11 Reconciliation of EBITDA excl. Identified Items to EBITDA, Net Income (Loss), Income (Loss) from Operations and Net Cash Provided by (Used for) Operating Activities Three Months Ended September 30, Three Months Ended June 30, Nine Months Ended September 30, 2026 2025 2026 2026 2025 (In millions of dollars) Net cash provided by operating activities $ 408 $ 182 $ 305 $ 619 $ 240 Changes in operating assets and liabilities and other (509) (895) (54) (592) (1,138) Deferred income taxes 119 (59) 20 105 (40) Net income (loss) 18 (772) 271 132 (938) Less: Other income, net 17 32 29 84 93 Interest expense (52) (41) (55) (163) (120) Benefit from (provision for) income taxes 10 3 (67) (24) (4) Income (loss) from operations 43 (766) 364 235 (907) Add: Depreciation and amortization 290 303 286 860 881 Other income, net 17 32 29 84 93 EBITDA $ 350 $ (431) $ 679 $ 1,179 $ 67 Add: Identified items 58 744 — 143 881 EBITDA excl. Identified Items $ 408 $ 313 $ 679 $ 1,322 $ 948 Operating income (loss) margin 1 % (27) % 11 % 3 % (11) % EBITDA margin excl. Identified Items 14 % 11 % 21 % 15 % 11 %
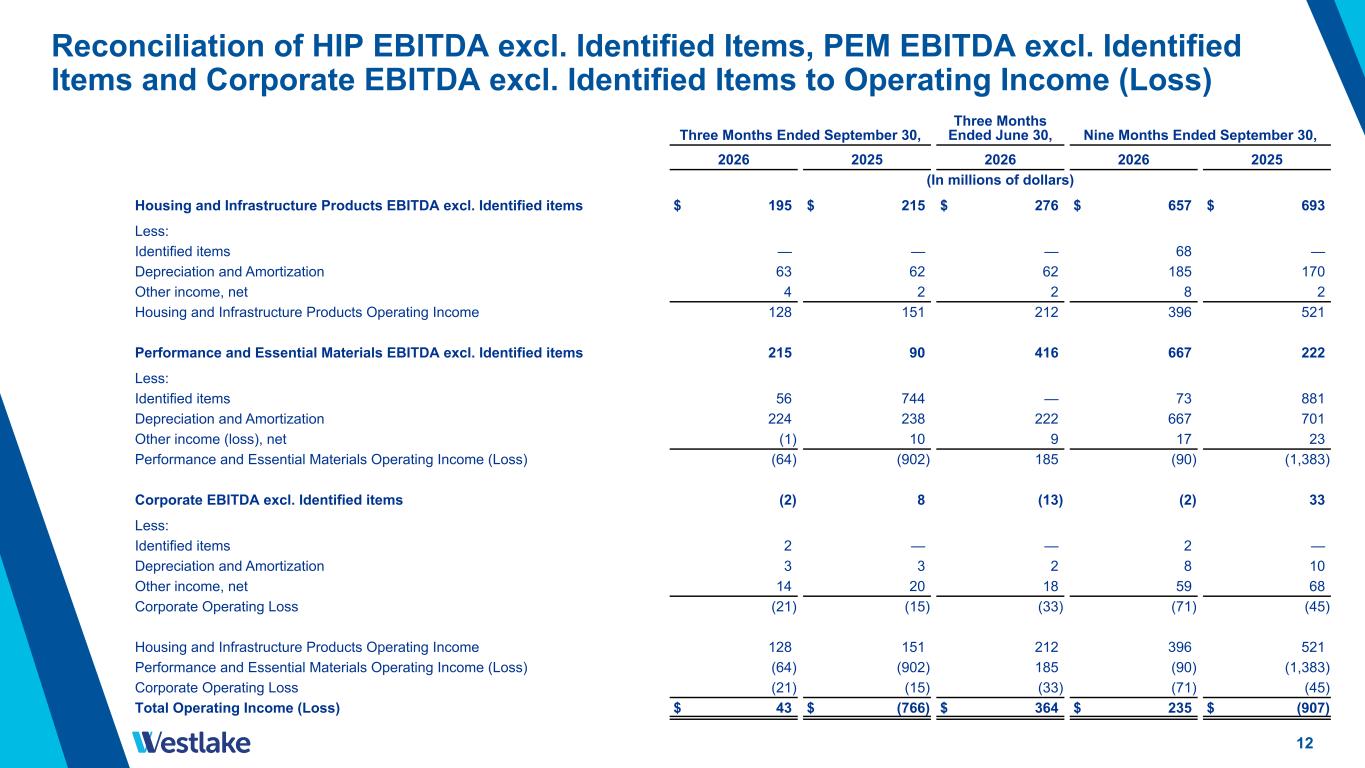
12 Reconciliation of HIP EBITDA excl. Identified Items, PEM EBITDA excl. Identified Items and Corporate EBITDA excl. Identified Items to Operating Income (Loss) Three Months Ended September 30, Three Months Ended June 30, Nine Months Ended September 30, 2026 2025 2026 2026 2025 (In millions of dollars) Housing and Infrastructure Products EBITDA excl. Identified items $ 195 $ 215 $ 276 $ 657 $ 693 Less: Identified items — — — 68 — Depreciation and Amortization 63 62 62 185 170 Other income, net 4 2 2 8 2 Housing and Infrastructure Products Operating Income 128 151 212 396 521 Performance and Essential Materials EBITDA excl. Identified items 215 90 416 667 222 Less: Identified items 56 744 — 73 881 Depreciation and Amortization 224 238 222 667 701 Other income (loss), net (1) 10 9 17 23 Performance and Essential Materials Operating Income (Loss) (64) (902) 185 (90) (1,383) Corporate EBITDA excl. Identified items (2) 8 (13) (2) 33 Less: Identified items 2 — — 2 — Depreciation and Amortization 3 3 2 8 10 Other income, net 14 20 18 59 68 Corporate Operating Loss (21) (15) (33) (71) (45) Housing and Infrastructure Products Operating Income 128 151 212 396 521 Performance and Essential Materials Operating Income (Loss) (64) (902) 185 (90) (1,383) Corporate Operating Loss (21) (15) (33) (71) (45) Total Operating Income (Loss) $ 43 $ (766) $ 364 $ 235 $ (907)
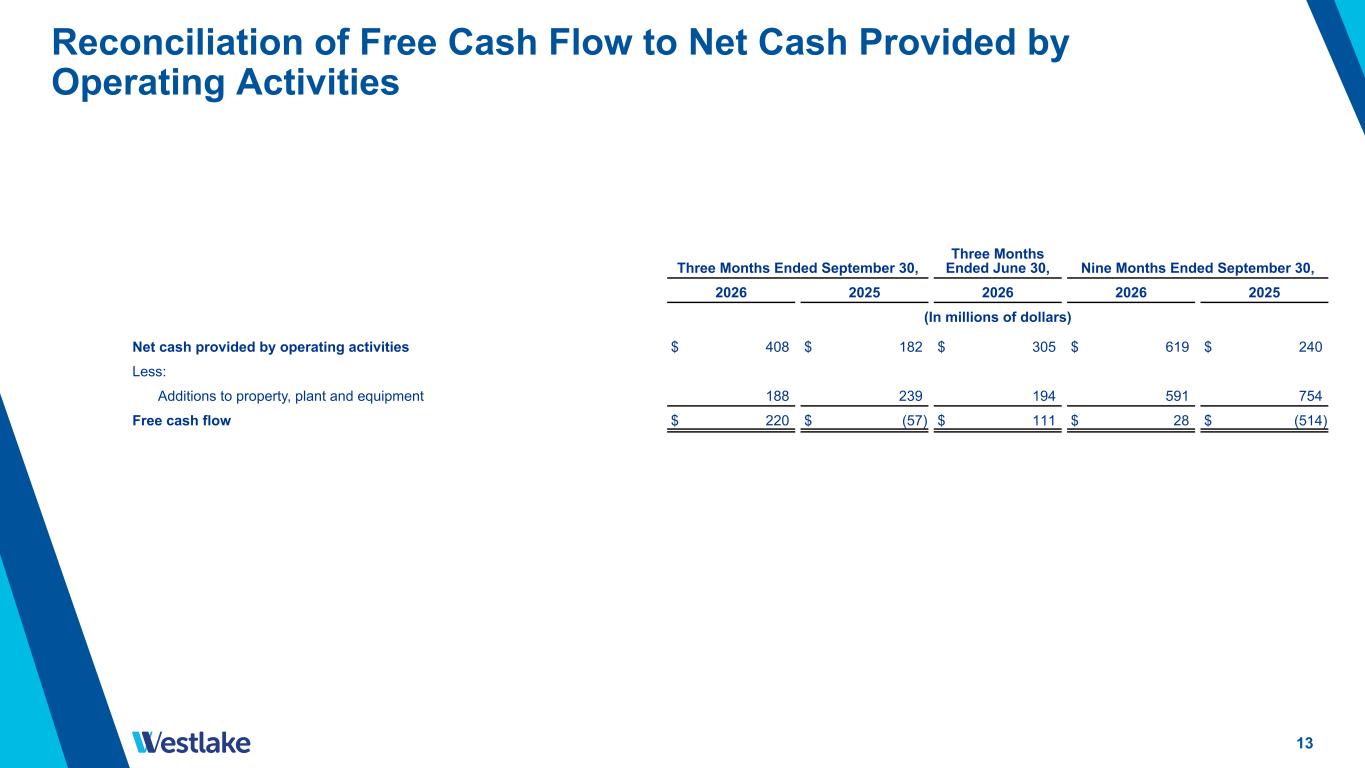
13 Reconciliation of Free Cash Flow to Net Cash Provided by Operating Activities Three Months Ended September 30, Three Months Ended June 30, Nine Months Ended September 30, 2026 2025 2026 2026 2025 (In millions of dollars) Net cash provided by operating activities $ 408 $ 182 $ 305 $ 619 $ 240 Less: Additions to property, plant and equipment 188 239 194 591 754 Free cash flow $ 220 $ (57) $ 111 $ 28 $ (514)
14 Safe Harbor Language This presentation contains certain forward-looking statements including statements regarding our cost savings objectives and our ability to maintain synergies, pricing and demand for our products and across the industrial and manufacturing sectors, global macroeconomic conditions, anticipated sales volumes and volume growth, industry outlook for both of our segments, our ability to execute our integrated strategy, projected benefits from the shutdown of certain of our PEM facilities, our cost control and efficiency efforts (such as achieving a $600 million uplift to EBITDA in 2026 from our three-pillar profitability improvement plan), our future operating results, including revenues and EBITDA, continuous improvement in PEM reliability and production, our expectations regarding previously communicated ranges of our HIP segment’s revenue and EBITDA margin for 2026, our competitive position, the effects of changing demographics in the markets that we serve, anticipated residential construction, repair and remodel activities and infrastructure spending growth, long-term housing market fundamentals, changes in sales mix of our products, our relationships with our customers and their adoption of our products, the benefits of our acquisition of the VCM/PVC production site in Wilhelmshaven, Germany, and the effects of the conflict in the Middle East, including the benefits of our energy and feedstock cost advantages in the North American chemicals market. Actual results may differ materially depending on factors, including, but not limited to, the following: general economic and business conditions; the cyclical nature of the chemical and building products industries; the availability, cost and volatility of raw materials and energy; uncertainties associated with the United States, European and worldwide economies, including those due to political tensions and conflict in the Middle East, Russia, Ukraine and elsewhere; uncertainties associated with climate change; the potential impact on the demand for ethylene, polyethylene and polyvinyl chloride due to initiatives such as recycling and customers seeking alternatives to polymers; current and potential governmental regulatory actions in the United States and other countries; industry production capacity and operating rates; the supply/demand balance for our products; competitive products and pricing pressures; instability in the credit and financial markets; access to capital markets; terrorist acts; operating interruptions; changes in laws or regulations, including trade policies; disruptions in global trade; the effects of government shutdowns; technological developments; information systems failures and cyber attacks; foreign currency exchange risks; our ability to implement our business strategies; creditworthiness of our customers; the effect and results of litigation and settlements of litigation; and other factors described in our reports filed with the Securities and Exchange Commission. Many of these factors are beyond our ability to control or predict. Any of these factors, or a combination of these factors, could materially affect our future results of operations and the ultimate accuracy of the forward-looking statements. These forward-looking statements are not guarantees of our future performance, and our actual results and future developments may differ materially from those projected in the forward-looking statements. Management cautions against putting undue reliance on forward-looking statements. Every forward-looking statement speaks only as of the date of the particular statement, and we undertake no obligation to publicly update or revise any forward-looking statements except as required by applicable law. Investor Relations Contacts Jon Baksht Senior Vice President & Chief Financial Officer Jeff Holy Vice President - Finance & Investor Relations Westlake Corporation 5444 Westheimer Road, Suite 101, Houston, Texas 77056 | 713-960-9111